Why Insurance Companies Make Low Offers After Accidents, And How to Fight Back
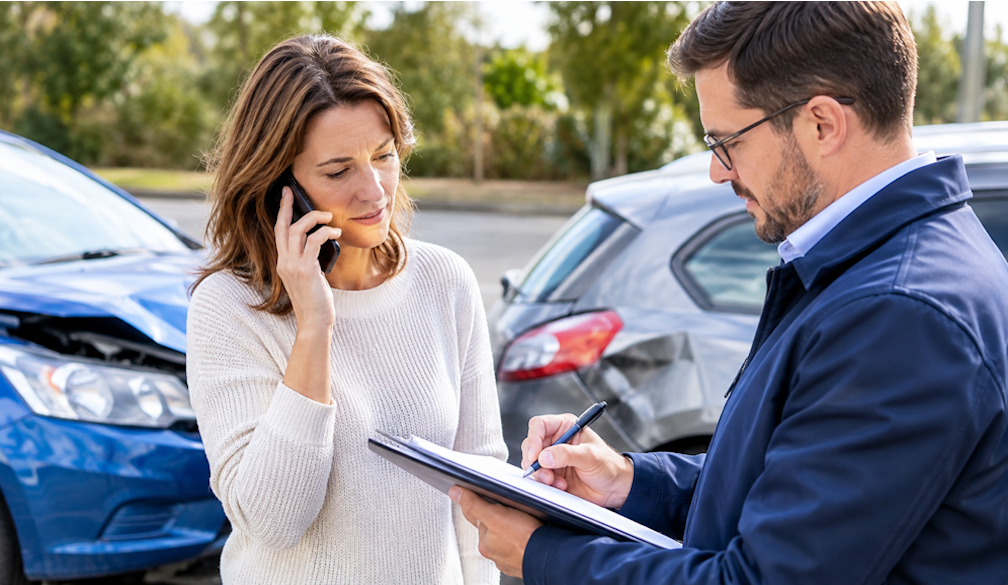
You open the envelope a few weeks after the crash, expecting a fair check, and the number inside barely covers your medical bills. That sting is common among accident victims, and it is rarely a mistake. The offer is an opening move in a negotiation you may not have known you were in.
Insurance companies are businesses first and helpers second. Every claim they pay reduces their profit, so adjusters learn to settle quickly and cheaply. Understanding how that system works is the first step toward getting what you are actually owed.
The Business Behind the Low Offer
An insurer collects premiums from millions of drivers and pays out when some of them get hurt. The gap between what comes in and what goes out is profit, and shareholders expect that gap to grow.
Because of this, adjusters often work under internal targets for how much a claim should cost. Their performance reviews may reward closing files fast and keeping payouts low, even when the injury is serious.
None of this makes every adjuster a villain. Many are polite and professional. Still, their employer’s interests and yours point in opposite directions, and you should never forget that during any phone call.
Why the First Offer Is Almost Always Low
The first offer is a test. Adjusters know that many injured drivers are stressed, behind on bills, and eager to move on. A quick check can look very tempting in that situation.
Insurers also count on the fact that most claimants do not know what their case is worth. If you do not know the value of future treatment or lost income, you cannot argue against a lowball figure.
Think of the first number as a starting bid. Adjusters usually leave room to move upward, because they expect a counteroffer from anyone who understands the process.
Common Tactics Adjusters Use
Some methods are subtle, and they work best when the victim is tired or in pain. Knowing them ahead of time makes them much easier to spot and resist.
One frequent move is asking for a recorded statement early. “Adjusters may steer your words toward admitting partial blame or downplaying your injuries, and a single casual comment can be used against you later,” explain the attorneys at Chopin law firm.
Another approach is blaming a preexisting condition. If you had back pain years ago, the insurer may claim the accident did not cause your current problem, even when a doctor says otherwise.
Delay is also a favorite. Slow responses and endless paperwork wear down your patience, and a victim who is desperate for money may accept far less than the claim deserves.
How Insurers Calculate What They Think You Deserve
Most companies use software that scores a claim based on injury codes, treatment length, and local settlement data. The program spits out a range, and adjusters aim for the bottom of it.
These programs often miss details that matter, such as chronic pain, emotional distress, or how an injury affects your job. A computer cannot see how a shoulder injury stopped a father from lifting his child.
That is why your own evidence matters so much. Strong documentation pushes the numbers up, because it shows facts the software never accounted for.
Steps You Can Take to Protect Your Claim
Preparation is your best defense, and most of it starts in the first days after the crash. The following habits make a real difference when it is time to negotiate:
- Photograph the vehicles, the road, and every visible injury at the scene
- Seek medical care right away, even if the pain feels minor
- Keep every receipt, bill, and prescription record in one folder
- Write daily notes about your pain, sleep, and missed activities
- Collect contact details from witnesses before they leave
- Share social media posts sparingly, since insurers often monitor them
- Decline recorded statements until you understand your rights
Each item builds a paper trail that supports your story. When an adjuster questions your injury, you can answer with dates, records, and photos instead of memory alone.
How to Respond to a Lowball Offer
Do not accept the first figure, and do not feel rushed by a deadline an adjuster invents. You have the right to take time and review the offer carefully.
Reply in writing with a counteroffer that lists your medical costs, lost wages, and future care. Explain why the insurer’s number falls short, and attach the proof that backs up each claim.
Stay calm and polite, because anger gives the other side an easy excuse to dismiss you. A firm, organized letter often earns more respect than an emotional phone call.
If the adjuster refuses to budge, ask for a written explanation of how they reached their figure. Those reasons sometimes reveal mistakes or missing records that you can fix and use to your advantage.
When to Bring In a Lawyer
Not every claim needs an attorney. A small fender bender with no injuries can often be settled on your own with a little patience and good records.
However, serious injuries, disputed fault, or long recoveries change the picture. An experienced personal injury lawyer knows how adjusters think and what similar cases have paid in your area.
Most accident attorneys work on contingency, which means they only collect a fee if you win. That setup lets a family without extra savings still get strong representation.
Insurers also tend to take claims more seriously once a lawyer is involved. They know a trial is expensive, so they often raise offers to avoid one.
Final Thoughts
A low offer after an accident does not mean your claim is weak. It usually means the insurer is hoping you will settle before you know your real options.
Take your time, build your evidence, and treat the first number as the start of a conversation. With a little preparation, you can push back confidently and aim for a settlement that truly covers what the accident cost you.

 Emma Fawcett, CEO of Compare Club